

Dollar-Rupee at 60? Or 172?
Jan, 25, 2020 By Vikram Murarka 0 comments

NOTE 1: This is not a strictly predictive report. This is more of an exploration of possible multi-decade trends for Dollar-Rupee. It aims to lay out two main possibilities (of either Rupee strength towards 60 against the US Dollar, or weakness towards 172) before policy makers; and to suggest that we, as a country, should choose the path of Rupee strength.
NOTE 2: As per our analysis in Chart 6a and Chart 6b herein, the post-Independence rise in USD-INR might have already gotten over at 74.4825 in Oct-2018. The validity of this analysis hinges on the acceptance of a particular rare phenomenon. We are accepting this rare phenomenon because
(A) acceptance thereof allows the Rupee movement since 2008 to fit in with some other movements in the global currency market and (B) although rare, the phenomenon cannot be rejected (a bit like, although rare, a white peacock is accepted as a peacock, not rejected.)
NOTE 3: We are sharing this analysis because (A) we sincerely believe it has merit and (B) there is a very important policy implication to be considered at the highest level (please refer Note 1 above).
NOTE 4: There is a 30-50% chance that our analysis is wrong. But, there is also a 50-70% chance that the analysis is right. Even if the analysis is wrong and USDINR has not already seen a top at 74.4825 in Oct-2018, there is a very good chance (near 70%) that the post-Independence weakness of the Rupee can naturally come to an end anywhere between 75-77. That is, if the economic orthodoxy of the authorities does not stand in the way and disrupt the natural movement of the USDINR. The alternative would be to see Rupee weakness continue into perpetuity.
You may also like:

In our 10-Dec-25 report (USDJPY 156.70), we expected the USDJPY to trade within 154-158 region till Jan’26 before eventually rising in the long run. In line with our view, the pair limited the downside to … Read More
Our last report (03-Oct-26, UST10Y 5.28%) warned of increased chances of Brent rising towards $135-145, US Core PCE rising towards 4.5-5.0% and the US10Yr rising towards 5.80% (Dec-26) and 6.00% (Aug-27). While Brent has risen to nearly $117 and the Core PCE (Aug-27) has inched up to 3.01%, we find that US Yields have fallen across …. Read More
In our October 2026 report (5-Oct-26, Brent @ $101.71), we had stated Brent would be structurally bullish for the long term based on the technical analysis, within which a test of $115 was expected in Oct-26, followed by a test of $134 by Dec-26 and eventually targeting $145 in 2027. In line with our expectation, Brent did test $117.45, slightly higher than our expected $115 in Oct-26. … Read More
In our September 2026 report (4-Sep-26, EURUSD 1.1620), we revised our Euro forecast upwards due to lack of followthrough selling below 1.14. We expected the Euro to range between 1.1980-1.13 for the next 1yr. However, in line with our earlier bearish outlook, the Euro fell sharply to …. Read More
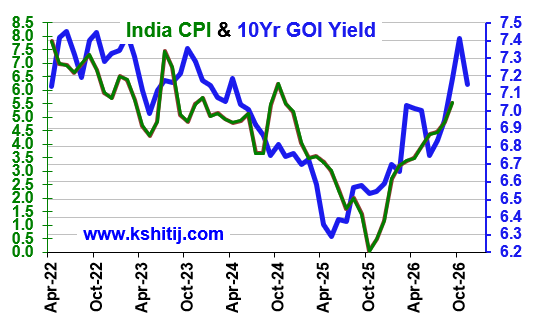
In our 06-Oct-26 report (10Yr GOI 7.19%%), we examined the possibility of the RBI not raising the Repo rate, even though 91% of the market expected it to raise. We were barking up the wrong tree as the RBI did indeed raise the Repo on 07-Oct. Thankfully, our forecasted rise in Brent to $115-120 did materialize well with Brent touching a high of $118 on 30-Oct. We also forecasted that … Read More
Our November ’26 Dollar Rupee Monthly Forecast is now available. To order a PAID copy, please click here and take a trial of our service.