
How do our forecasts compare with those of our peers?
Mar, 06, 2018 By Saandhy Ganeriwala 0 comments

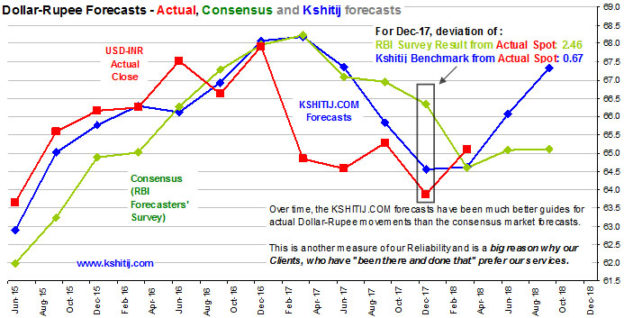
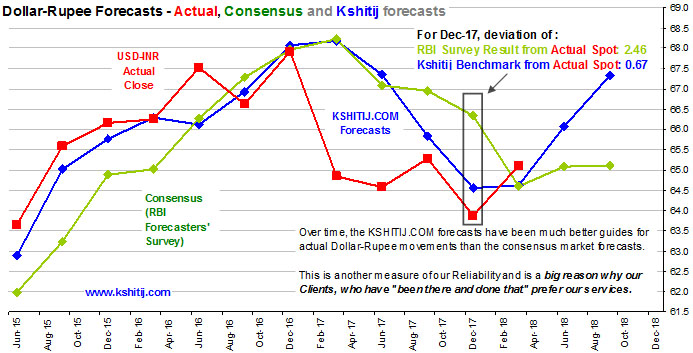
Anyone wanting to evaluate our service would ask the above question. As an answer, we compare our forecasts with the results of the RBI’s bimonthly Survey of Professional Forecasters (SPF), which captures the market’s consensus expectation for USDINR for forthcoming quarters.
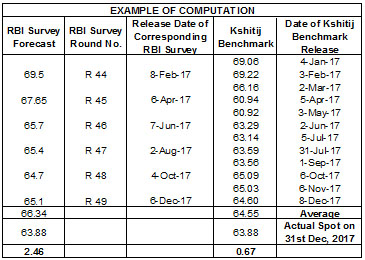
As an example, for the USDINR rate at end of Dec ‘17, there were 6 forecasts which the RBI’s survey pool of professional forecasters made. These are displayed in the 1st column of the adjacent table. The mean of these 6 forecasts ie 66.34 can be regarded as the market’s consensus forecast for USDINR for 31ST Dec, 2017. Correspondingly, over the preceding year, we had made 12 Kshitij monthly forecasts for the USDINR rate expected to prevail on 31ST Dec, 2017 (see column 4). The mean of these 12 Kshitij forecasts ie 64.55 ultimately turned out to be closer to the actual spot rate (63.88) of USDINR on 31ST Dec, 2017.
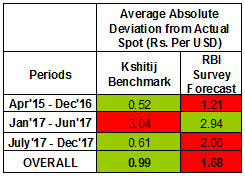
In fact, over the period Apr-2015 till Dec-2017, the average absolute deviation of Kshitij forecasts from the actual quarter end spots has been Re 0.99 per USD, much narrower than the deviation of the RBI SPF’s forecasts of Rs 1.68 per USD.
We might be the first and only forecasting service to carry out such an analysis, comparing ourselves with our peers, as a means to judge how much value we can add compared to others. This is part of our effort to increase our Reliability. Please also read:
How much of the market movement do our forecasts capture
Stop Press! Or, why KSHITIJ.COM is Reliable
View our March Economic Calendar.
Saandhy Ganeriwala
Saandhy is a postgraduate in Economics, but like all good market-men, he seeks confirmation from technical analysis charts for his macroeconomic ideas. His research is a good mix of charts, stats and econ. Apart from that, he calls himself a news junkie and an occasional writer.
You may also like:
In our 10-Dec-25 report (USDJPY 156.70), we expected the USDJPY to trade within 154-158 region till Jan’26 before eventually rising in the long run. In line with our view, the pair limited the downside to … Read More
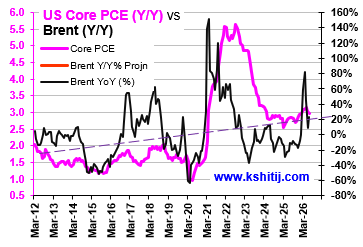
In our last report (04-Sep-26, UST10Y 4.77%) we had noted chances of a slowdown ahead but since Crude could spike up, we retained our view of the US10Yr rising to 5.10% by Nov-26 and 5.40% by Mar-27. As it turns out, Brent did indeed rise to …. Read More
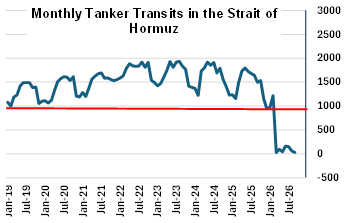
In our September 2026 report (11-Sep-26, Brent @ $103.84), we had expected Brent to range within $90-115 for the next 1year. Prices were expected to remain elevated, primarily driven by the low volume of vessel transit in the Strait of Hormuz. Brent indeed traded within $109.97 and $90.70 in Sep-26, within our expected range. … Read More
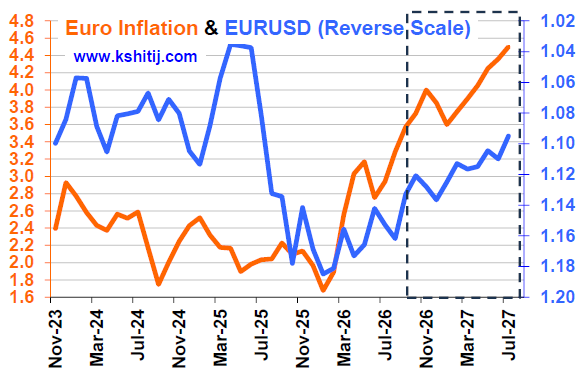
In our September 2026 report (4-Sep-26, EURUSD 1.1620), we revised our Euro forecast upwards due to lack of followthrough selling below 1.14. We expected the Euro to range between 1.1980-1.13 for the next 1yr. However, in line with our earlier bearish outlook, the Euro fell sharply to …. Read More
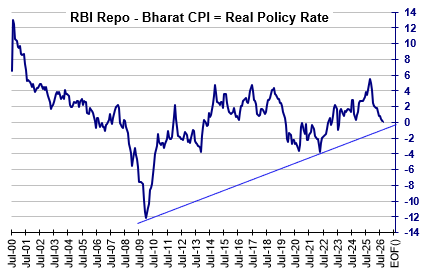
In our 10-Sep-26 report (10Yr GOI 6.98%), we had noted that the Long end of the Curve, viz. the 10Yr GOI was rising due to a number of factors. We said, “Whether the RBI will raise rates on 07-Oct will depend on whether Crude happens to be breaking higher or would have cooled off from $105 to $95” … Read More
Our October ’26 Dollar Rupee Quarterly Forecast is now available. To order a PAID copy, please click here and take a trial of our service.