

How do our forecasts compare with those of our peers?
Mar, 06, 2018 By Saandhy Ganeriwala 0 comments

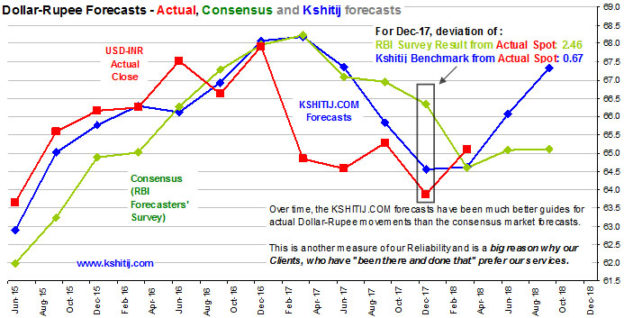
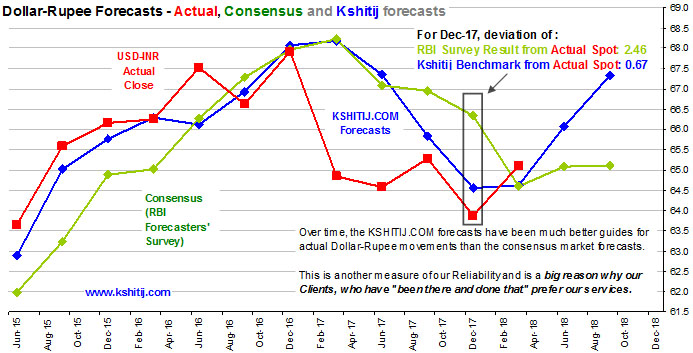
Anyone wanting to evaluate our service would ask the above question. As an answer, we compare our forecasts with the results of the RBI’s bimonthly Survey of Professional Forecasters (SPF), which captures the market’s consensus expectation for USDINR for forthcoming quarters.
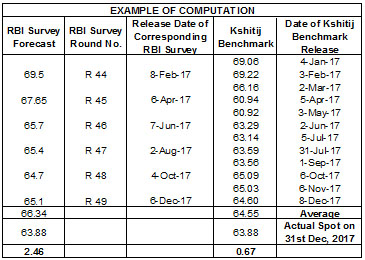
As an example, for the USDINR rate at end of Dec ‘17, there were 6 forecasts which the RBI’s survey pool of professional forecasters made. These are displayed in the 1st column of the adjacent table. The mean of these 6 forecasts ie 66.34 can be regarded as the market’s consensus forecast for USDINR for 31ST Dec, 2017. Correspondingly, over the preceding year, we had made 12 Kshitij monthly forecasts for the USDINR rate expected to prevail on 31ST Dec, 2017 (see column 4). The mean of these 12 Kshitij forecasts ie 64.55 ultimately turned out to be closer to the actual spot rate (63.88) of USDINR on 31ST Dec, 2017.
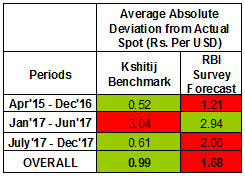
In fact, over the period Apr-2015 till Dec-2017, the average absolute deviation of Kshitij forecasts from the actual quarter end spots has been Re 0.99 per USD, much narrower than the deviation of the RBI SPF’s forecasts of Rs 1.68 per USD.
We might be the first and only forecasting service to carry out such an analysis, comparing ourselves with our peers, as a means to judge how much value we can add compared to others. This is part of our effort to increase our Reliability. Please also read:
How much of the market movement do our forecasts capture
Stop Press! Or, why KSHITIJ.COM is Reliable
View our March Economic Calendar.
Saandhy Ganeriwala
Saandhy is a postgraduate in Economics, but like all good market-men, he seeks confirmation from technical analysis charts for his macroeconomic ideas. His research is a good mix of charts, stats and econ. Apart from that, he calls himself a news junkie and an occasional writer.
You may also like:
In our 10-Dec-25 report (USDJPY 156.70), we expected the USDJPY to trade within 154-158 region till Jan’26 before eventually rising in the long run. In line with our view, the pair limited the downside to … Read More
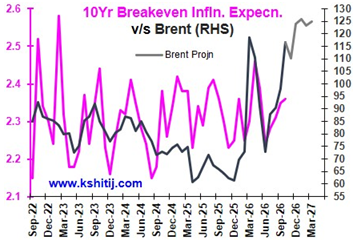
Our last report (03-Oct-26, UST10Y 5.28%) warned of increased chances of Brent rising towards $135-145, US Core PCE rising towards 4.5-5.0% and the US10Yr rising towards 5.80% (Dec-26) and 6.00% (Aug-27). While Brent has risen to nearly $117 and the Core PCE (Aug-27) has inched up to 3.01%, we find that US Yields have fallen across …. Read More
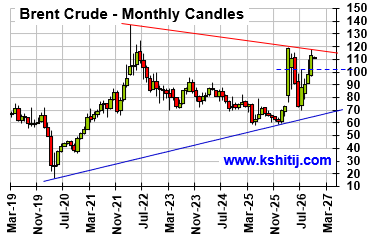
In our October 2026 report (5-Oct-26, Brent @ $101.71), we had stated Brent would be structurally bullish for the long term based on the technical analysis, within which a test of $115 was expected in Oct-26, followed by a test of $134 by Dec-26 and eventually targeting $145 in 2027. In line with our expectation, Brent did test $117.45, slightly higher than our expected $115 in Oct-26. … Read More
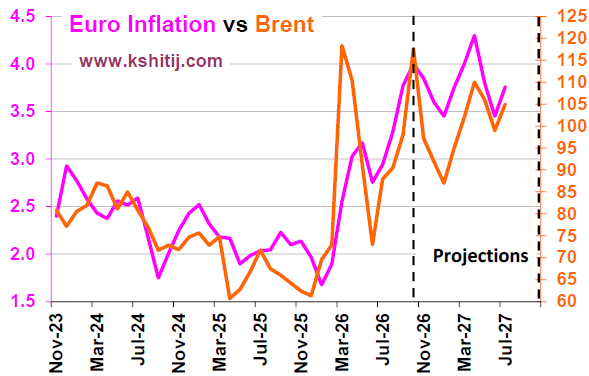
In our October 2026 report (9-Oct-26, EURUSD 1.1250), we revised our Euro forecast downwards on a decline below 1.13 and expected a fall towards 1.10-1.0875 by the next year. Rising crude prices were a concern and were expected to raise the US and Euro yields further, along with the inflation figures. The Euro has been declining while below 1.13 and has tested
1.11 so far. Both the ECB and the FED kept policy rates unchanged in the Oct-26 meeting, while the markets expect a rate hike in the Dec-26 meeting by both central banks. …. Read More
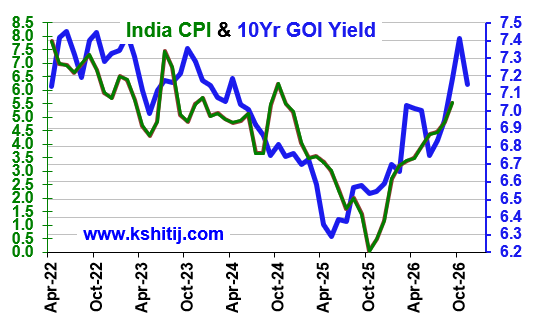
In our 06-Oct-26 report (10Yr GOI 7.19%%), we examined the possibility of the RBI not raising the Repo rate, even though 91% of the market expected it to raise. We were barking up the wrong tree as the RBI did indeed raise the Repo on 07-Oct. Thankfully, our forecasted rise in Brent to $115-120 did materialize well with Brent touching a high of $118 on 30-Oct. We also forecasted that … Read More
Our November ’26 Dollar Rupee Monthly Forecast is now available. To order a PAID copy, please click here and take a trial of our service.