

Drawbacks of Common Hedging Methods
Aug, 08, 2012 By Vikram Murarka 0 comments

 Forex risk management is a frustrating experience for most companies. There seem to be a thousand things that can go wrong at any time - the economy, the market, the forecasts, the regulations, the shipment and payment dates - and generally they do seem to go wrong all together, all the time, every time. If by any chance, or maybe by design, there is profit in any one year, it does not seem to last. Losses, when they inevitably come, tend to wipe out the profits of earlier years. Little wonder that most companies tend to give up on forex risk management in disgust, saying, "Forex is not our business!"
We disagree. Forex is very much the business of every importer and exporter. And, tackled with a common sense business approach, it can even add to the bottomline instead of constantly subtracting from it. But, that is material for another article. In this article, we shall look at how companies generally deal with forex risk management, and what problems they face.
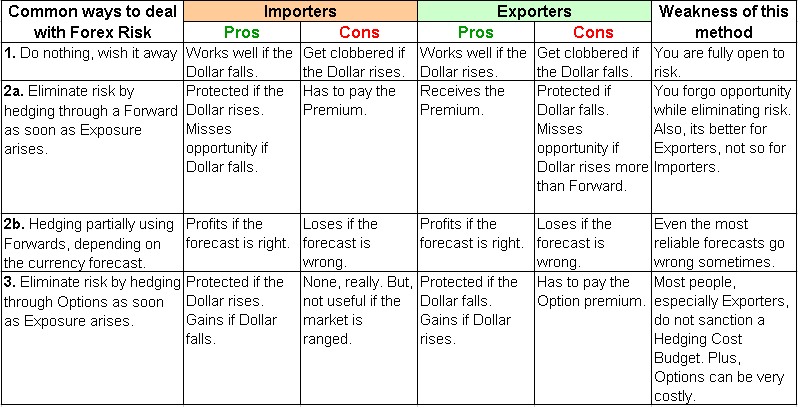
Method 1 - Do nothing
The most common way to deal with forex risk, of course, is to wish it away, to do nothing. But sadly, as the School of Hard Knocks has taught all of us, avoiding a problem, turning a blind eye to it never works in the long run.
Method 2a - Hedge 100% on Day 1 with Forwards
The second most common way to deal with the issue is to hedge away the forex risk, by closing the original exposure or position straight away, usually with a forward contract, so that the risk is eliminated. This is a simplistic solution, commonly prescribed by textbooks and "purists" who espouse the belief that "forex is not your business." The implicit suggestion is that the company is incapable of managing forex risk.
The problem with this method is that although risk is eliminated no doubt, one ends up sacrificing all potential profit as well. An associated problem with this method is that it is easy to adopt for the exporter who earns the forward premium, but is difficult for the importer who has to pay the same premium.
Method 2b - Selective hedging with Forwards
A variation to this method is to hedge sometimes and not to hedge at other times, based on the available market forecasts.
The problem with this method is that one doesn't know whether the forecast is going to be right or wrong. One cannot have an idea of the chances of success. In case the forecast is prepared by the internal risk management team of the company, there is an additional risk of the forecast turning out to be biased. For instance, there's a danger that an importer will be biased towards a weaker Dollar while an exporter would say that the Dollar is going to rise. In this, it helps to take a forecast from an external, professional forecaster, whose work is considered reliable. For instance, 72% of our forecasts are reliable.
Method 3 - Hedge exclusively through Options
The third, much less common way to hedge against forex risk is to use Options as the hedging tool, rather than the forward contract. This is a better way, no doubt, but it is still not the best way. The benefit of course, is that Options allow the company to partake of potential profit if the market moves in its favour, while eliminating the risk of an unfavourable move. It is, in a manner, the best of both worlds. The sad part is that options tend to be costly and are profitable only in trending markets. Further, most companies, especially exporters (who are used to receiving forward premium) do not have a hedging cost budget, which would enable them to pay the premium for buying options.
What is the way out?
Very well, we've pointed out the flaws in all the common risk management methods. Does this mean there's no hope for beleaguered company managements? Thankfully, there is definitely a way out, and it works. In fact, it has worked for the last six years in various market conditions. We call it the KSHITIJ Hedging Method. It is built on common sense business principles and has been formulated after years of experience and trial and error.
Most importantly, it rejects the fatalistic belief that "forex is not my business." Instead we believe that forex is very much the business of every importer and exporter. And, there is no business issue that cannot be dealt with efficiently if approached proactively. The KSHITIJ Hedging Method is built on the belief that something proper can definitely be done in forex risk management, that the effort is not destined for failure.
You may also like:
In our 10-Dec-25 report (USDJPY 156.70), we expected the USDJPY to trade within 154-158 region till Jan’26 before eventually rising in the long run. In line with our view, the pair limited the downside to … Read More
Our last report (03-Oct-26, UST10Y 5.28%) warned of increased chances of Brent rising towards $135-145, US Core PCE rising towards 4.5-5.0% and the US10Yr rising towards 5.80% (Dec-26) and 6.00% (Aug-27). While Brent has risen to nearly $117 and the Core PCE (Aug-27) has inched up to 3.01%, we find that US Yields have fallen across …. Read More
In our October 2026 report (5-Oct-26, Brent @ $101.71), we had stated Brent would be structurally bullish for the long term based on the technical analysis, within which a test of $115 was expected in Oct-26, followed by a test of $134 by Dec-26 and eventually targeting $145 in 2027. In line with our expectation, Brent did test $117.45, slightly higher than our expected $115 in Oct-26. … Read More
In our October 2026 report (9-Oct-26, EURUSD 1.1250), we revised our Euro forecast downwards on a decline below 1.13 and expected a fall towards 1.10-1.0875 by the next year. Rising crude prices were a concern and were expected to raise the US and Euro yields further, along with the inflation figures. The Euro has been declining while below 1.13 and has tested
1.11 so far. Both the ECB and the FED kept policy rates unchanged in the Oct-26 meeting, while the markets expect a rate hike in the Dec-26 meeting by both central banks. …. Read More
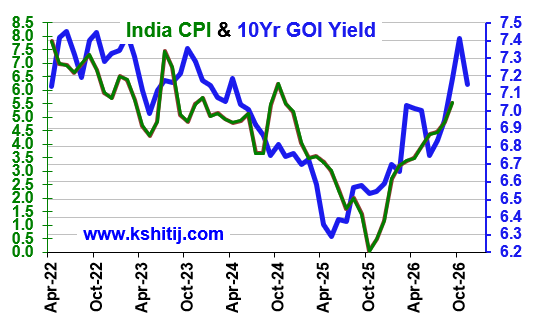
In our 06-Oct-26 report (10Yr GOI 7.19%%), we examined the possibility of the RBI not raising the Repo rate, even though 91% of the market expected it to raise. We were barking up the wrong tree as the RBI did indeed raise the Repo on 07-Oct. Thankfully, our forecasted rise in Brent to $115-120 did materialize well with Brent touching a high of $118 on 30-Oct. We also forecasted that … Read More
Our November ’26 Dollar Rupee Monthly Forecast is now available. To order a PAID copy, please click here and take a trial of our service.