

How paying Option Premium can actually be profitable
Feb, 16, 2008 By Vikram Murarka 0 comments

It is an open secret that every Corporate Hedger wants to pay no more than Zero for an Option that he buys. Banks oblige by constructing “zero cost” strategies. The concept of zero cost structures has become so ingrained in the general psyche of the market that when, at a seminar, we suggested buying Call Spreads at a cost, an experienced Hedger asked, “But, aren't Call Spreads supposed to be zero cost!” As if that is a cast-in-stone rule.
Like anyone else, we would love to be able to buy cheap Options. However, at the same time we are open to the idea of not only paying premium, but also the idea of paying higher premium, if there is an opportunity to make greater profits thereby. If this sounds strange, perhaps this trade example will illustrate.
In-the-Money Put Option
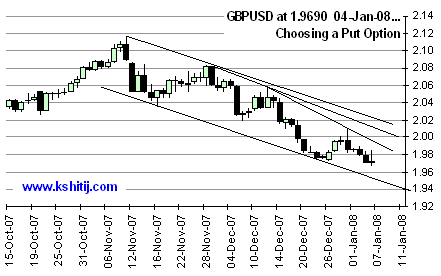
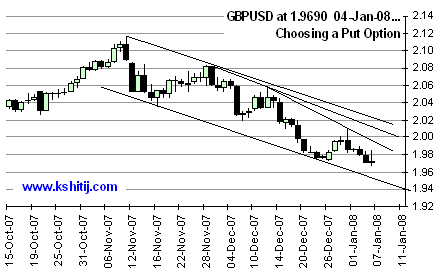
The GBP-USD was trading near 1.9690 on the morning of 04-Jan-08 , looking to fall towards 1.95 over a 1-month period and possibly towards 1.90 over 3-4 months. While an eventual fall looked pretty certain, an interim rally towards 1.98-99 could not be ruled out.
The idea, therefore, was to buy a Put Option, rather than to sell GBPUSD Forward. But, the Strike rate and the tenor needed to be figured out. We evaluated a combination of two strikes and two tenors.
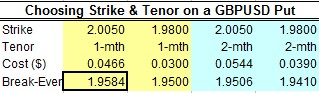 Both the strikes we evaluated were In-the-Money, at 2.0050 and 1.9850, as compared to the then At-the-Money-Forward rate of 1.9674 (Spot being 1.9690) for 1-month. The tenors considered were 1-month and 2-months. The cost and breakevens for each are given in the table alongside. We eventually decided to buy a GBPUSD Put, Strike 2.0050 for 1-month. This was despite the fact that the Premium (0.0466) for the 2.0050 1-mth Put was higher than those for the 1.98 1-mth and 1.98 2-mth Puts. The deciding factor was the Breakeven, which at 1.9584 was the highest for the combination we chose.
Better Off
As it turns out, our currency view proved to be correct and GBPUSD fell to 1.9520 by 11-Jan, just a week after we bought the 2.0050 Put. We did a position review. The Vols had fallen from 9.85% on 04-Jan to 9.08% on 11-Jan. Thus, we were making money on the currency (GBPUSD had fallen 0.86%) as well as on the Vols. At the same time, we had not lost a lot of time-value, because our initial target of 1.95 had been more or less achieved in just 7 days. We decided to unwind.
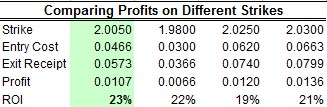 We had made a profit of 107 pips against an initial cost of 466 pips, a return of 23%. This was higher, both in pips as well as percentage terms, than what we would have made had we bought a 1.98 Put where we would have paid a smaller premium of 300 pips. Cheap (and Zero Cost) Options are not necessarily the only way to be profitable.
Sometimes it pays to pay more because you can end up making more!
You may also like:
In our 10-Dec-25 report (USDJPY 156.70), we expected the USDJPY to trade within 154-158 region till Jan’26 before eventually rising in the long run. In line with our view, the pair limited the downside to … Read More
Our last report (03-Oct-26, UST10Y 5.28%) warned of increased chances of Brent rising towards $135-145, US Core PCE rising towards 4.5-5.0% and the US10Yr rising towards 5.80% (Dec-26) and 6.00% (Aug-27). While Brent has risen to nearly $117 and the Core PCE (Aug-27) has inched up to 3.01%, we find that US Yields have fallen across …. Read More
In our October 2026 report (5-Oct-26, Brent @ $101.71), we had stated Brent would be structurally bullish for the long term based on the technical analysis, within which a test of $115 was expected in Oct-26, followed by a test of $134 by Dec-26 and eventually targeting $145 in 2027. In line with our expectation, Brent did test $117.45, slightly higher than our expected $115 in Oct-26. … Read More
In our October 2026 report (9-Oct-26, EURUSD 1.1250), we revised our Euro forecast downwards on a decline below 1.13 and expected a fall towards 1.10-1.0875 by the next year. Rising crude prices were a concern and were expected to raise the US and Euro yields further, along with the inflation figures. The Euro has been declining while below 1.13 and has tested
1.11 so far. Both the ECB and the FED kept policy rates unchanged in the Oct-26 meeting, while the markets expect a rate hike in the Dec-26 meeting by both central banks. …. Read More
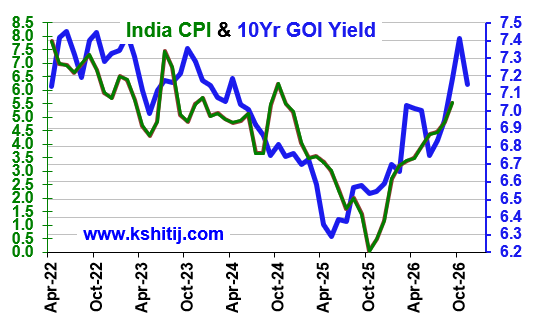
In our 06-Oct-26 report (10Yr GOI 7.19%%), we examined the possibility of the RBI not raising the Repo rate, even though 91% of the market expected it to raise. We were barking up the wrong tree as the RBI did indeed raise the Repo on 07-Oct. Thankfully, our forecasted rise in Brent to $115-120 did materialize well with Brent touching a high of $118 on 30-Oct. We also forecasted that … Read More
Our November ’26 Dollar Rupee Monthly Forecast is now available. To order a PAID copy, please click here and take a trial of our service.